Real estate agents live in constant motion. One hour they tour a property, the next they draft an offer, and by evening they reconcile a commission check. Somewhere in that chaos, the books need to balance. That is where a bookkeeping VA services provider steps in. Instead of drowning in receipts and split statements, agents can hand the numbers to a professional who understands the unique rhythm of real estate income. This article explores how virtual assistant bookkeeping services for real estate agents and brokers keep commissions, expenses, and mileage in order.
A good bookkeeper does more than record numbers. They create a system that matches how an agent actually earns. Real estate income arrives in bursts, often with strings attached. A broker takes a cut. A referral partner wants their share. The IRS wants its portion. Without a clear process, even a successful agent can feel broke by February.
Why Real Estate Numbers Are Not Like Other Numbers
The normal flow in a small business will involve selling a good or a service and making a revenue entry. When a real estate agent gets a commission through closing deals, they are normally required to share it with a broker, a group, or a referrer. The flow will be inconsistent. There may be three closures in one month and zero closures in the next.
An expert can know how to make such entries. An entry should include tracking the closing statement, applying the right splitting ratio, and making the net deposit entry. Business expenses will need to be separated from personal expenses, especially in cases where an agent uses their own car for showings or office space in their own house.
The splitting ratios are not the end of complexity. Marketing, photography, staging, and other software subscriptions are paid out-of-pocket by agents. Traveling miles in a week is usually common. All these have a tax consequence, but only when done according to the guidelines of the specialist.
Stop letting split statements pile up on your desk.
Let Keach Virtual Assistant turn those numbers into clear reports.
The Commission Split Puzzle
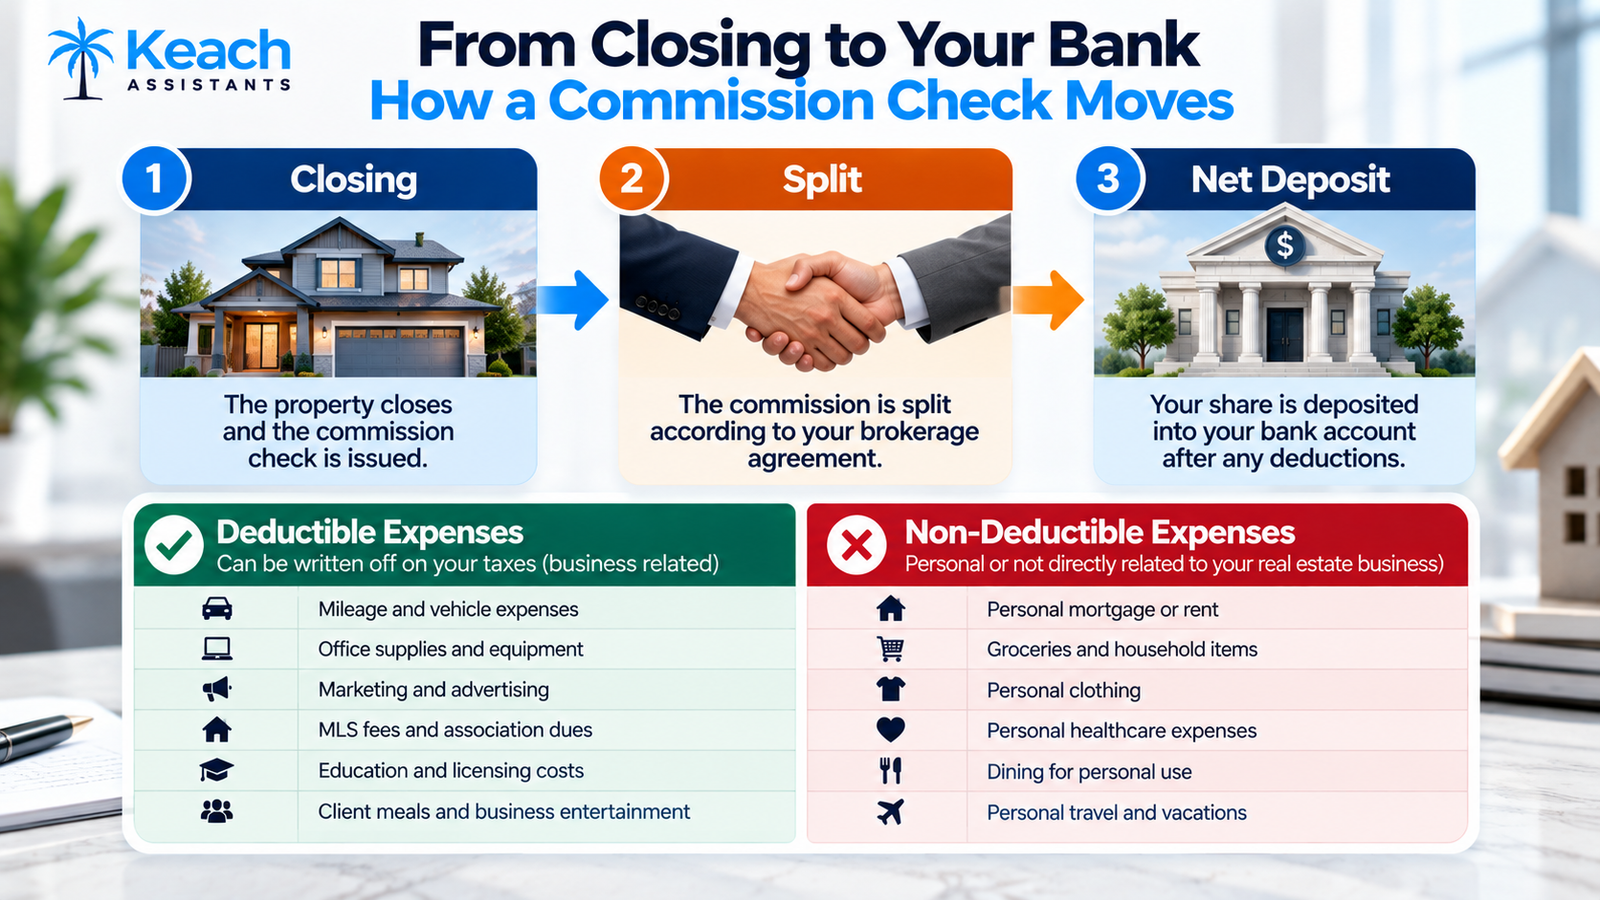
Commission splits are the heart of real estate accounting. When a deal closes, the title company or broker disburses funds. The agent might receive 70 percent, the broker 30 percent. Or the split might change based on a tiered cap. The process of how real estate virtual assistant bookkeepers track commission split payments begins with the closing statement. They create a liability account for the broker’s share and an income account for the agent’s share. This ensures the profit and loss statement reflects true earnings, not gross commission.
Tracking splits manually is a recipe for errors. It is easy to forget a referral fee or misplace a closing statement. A professional sets up a repeatable process. Each closing gets its own entry. The broker’s portion is recorded as a payable until it is paid. The agent’s portion is recorded as income. If the broker pays the agent directly and then invoices for their share, the VA tracks that too. This level of detail means the agent always knows their true net.
Tracking Expenses and Mileage Without the Mess
Real estate agents drive a lot. They also buy signs, pay for listing photos, and subscribe to CRM software. Tracking these expenses is tedious, but it is essential for deductions. A bookkeeping VA services provider sets up a system where receipts are scanned or forwarded automatically. Real estate agent expense tracking and mileage bookkeeping VA services cover everything from gas receipts to listing fees.
They categorize each expense, from mileage to marketing, so nothing gets lost. Mileage is a big one. The IRS allows a standard mileage rate, but only if the agent keeps a log. A VA can manage a mileage tracking app and reconcile it with the books monthly. For agents using QuickBooks, the VA ensures that expense tracking for real estate agents in QuickBooks is accurate and audit-ready.
The system does not have to be complicated. A shared folder for receipts, a mileage app that runs in the background, and a monthly review call are often enough. The VA does the heavy lifting. They match receipts to bank statements, flag duplicate charges, and question anything that looks off. They also categorize expenses correctly, which matters at tax time. A marketing expense is not the same as a vehicle expense. Getting these categories right can save an agent thousands of dollars over a year.
How Real Estate Income Flows
When It Is Time to Bring in Help
Many agents start by doing their own books. It feels manageable at first. But as the business grows, the hours add up. So when is it time to hire a remote bookkeeper? If you are spending more than a few hours a month on spreadsheets, or if you have ever missed a quarterly tax payment, it is time. Freelancers often ask: Do freelancers really need a virtual bookkeeper? The answer depends on volume. A solo agent with a handful of deals might get by with software. But a busy agent or a small team needs a human who can catch errors and plan for taxes.
The decision often comes down to opportunity cost. Every hour spent categorizing receipts is an hour not spent showing properties or negotiating deals. A professional bookkeeper costs less than the commission on a single lost deal. They also provide peace of mind. Knowing that quarterly taxes are filed and that the books are clean allows an agent to focus on their clients.
Invoices, Late Payments, and the VA Role
Can a bookkeeping virtual assistant handle invoices and late payments? Absolutely. While real estate commissions usually arrive at closing, agents often have other income streams. They may bill for consultations, management services, or referral fees. The virtual assistant can send invoices, monitor deadlines, and deal with any overdue payments. The VA can also take care of accounts payable to make sure that photographers, stagers, and other vendors get their bills paid on time. This protects the agent’s reputation and keeps cash flow going smoothly.
Late payments are a fact of life in any business. A client might forget to pay an invoice for a consultation. A property management client might be slow to settle. A VA can set up automatic reminders and follow up politely but persistently. They can also flag accounts that are consistently late, so the agent can decide whether to change their terms. On the payable side, a VA ensures that bills are paid on time, avoiding late fees and damaged relationships.
Reading Your P&L Without a Finance Degree
How do you read a P&L report from your QuickBooks bookkeeper? It starts with understanding the top line and the bottom line. The top line is gross commission income. The bottom line is net profit after expenses and splits. A good VA does not just hand over a report. They walk the agent through it. They highlight trends, like a spike in marketing costs or a dip in closings. They explain what each category means and how it affects taxes. This turns a confusing spreadsheet into a roadmap for business decisions.
The P&L is not just a tax document. It is a story about the business. It shows which months are strong and which are weak. It shows whether marketing spend is paying off. It shows if expenses are creeping up faster than income. An agent who understands their P&L can make smarter choices. They might decide to cut a subscription that is not used. They might invest more in a marketing channel that is working. Without this report, these decisions are guesses.
Cash vs Accrual: Which Method Fits?
Cash vs accrual: Which method should outsourced bookkeeping follow? For most real estate agents, cash basis is simpler. You record income when the check hits the bank and expenses when you pay them. Accrual basis records income when the deal closes, even if payment is delayed. Accrual gives a more accurate picture of long-term profitability, but it requires more work. A bookkeeping VA services provider can help you choose based on your business structure and tax goals. Many agents start with cash and switch to accrual as they grow.
The choice affects more than just the books. It affects how an agent plans for taxes. Cash basis can create a false sense of security if a big commission arrives in December, but the expenses for that deal are not paid until January. Accrual basis smooths out these timing issues, but it can also create tax liabilities before the cash is in hand. A professional can explain the pros and cons and help the agent make a decision that fits their situation.
Your books should not be a source of dread.
Let our virtual pros keep them tidy and tax-ready.
FAQs
How do I pay for a bookkeeping assistant?
The vast majority charge an hourly fee or a fixed monthly fee depending on the number of transactions and how complex your commission splits are.
Is it possible for an assistant to work together with my accountant?
Certainly. An experienced assistant cooperates with your CPA. He prepares the bookkeeping record and, reconciles the accounts, and provides a well-done file to your accountant.
What tools does a remote assistant use?
The most popular tool is QuickBooks Online. Other tools include Xero, Wave, or FreshBooks. It usually depends on which tool you are using.
Is it safe to give my financial information to a remote assistant?
A reputable assistant uses secure portals and 2FA. They have to sign an NDA and will never disclose your confidential information.
How far back can an assistant clean my bookkeeping record?
Most assistants can clean your record for the last one or two years. However, if your record is really untidy, an assistant might have to start with cleaning.